Category Archives: financial aid

Everything You Need to Know About the FAFSA


fafsa

Do you have questions about the FAFSA? or financial aid? Have you looked at the form and find some of the instructions complicated or ambiguous? You’re not alone. If you have a senior headed to college in the fall or you just want to be prepared for your future college bound teen, you should join tonight’s #CollegeCash chat. I’ll be the guest and @JodiOkun and I should be able to answer all your questions.

What: #CollegeCash

When: (Tonight) Thursday 8PM ET

Where: Twitter using #CollegeCash hashtag

Who: Host @JokiOkun and guest @SuzanneShaffer

Don’t forget to follow both of us on Twitter. If you’ve never attended a Twitter chat, here are some simple instructions.

How to Take Part in a Twitter Chat

See you there!


FAFSA Tips, Reminders, and Mistakes to Avoid


fafsaIt’s FAFSA time. “Yuck”, as one parent said. “Dreading, dreading, dreading” from another. “It’s my least favorite time of year (other than income taxes)”, said another. I get it. Nobody likes filling out federal forms, especially when money is on the line. And with the FAFSA, money is on the line.

Today I am sharing some of the best FAFSA advice I’ve found online. If you have a college bound teen, this information will be invaluable. Don’t just skim it, however; you need to read every last word. Not knowing can mean the difference between receiving aid and receiving a big fat zero. Trust me, I have learned from experience and listened to so many parents that neglected to do the research before completing the form.

Avoid These FAFSA Mistakes

My first piece of advice comes from Lynn O’Shaughnessy of The College Solution blog. Her advice is spot on and goes into great detail about some key points regarding marital status, household size, and reporting assets. It’s an easy to understand guide for parents and breaks the government lingo down into simple language.

Read more . . .

10 Tips to Prepare for the FAFSA

I wrote this article for TeenLife.com giving parents tips on what they need before completing the FAFSA. You want to be the first in line for financial aid. Students who complete the government form early are more likely to receive funds set aside by the colleges for financial aid. If you don’t complete the FAFSA, you won’t receive any aid. Everyone should file the FAFSA, even if you think you won’t qualify for federal aid.

Read more . . .

False FAFSA Assumptions

Jodi Okun of College Financial Aid Advisors wrote this piece for AboutMoney.com. One of the most common statements I hear from parents is, “I’m not going to file because we won’t qualify for financial aid”. Jodi points out the huge mistake in making this assumption and others.

Read more . . .

7 Legal Ways to Squeeze More Money Out of the FAFSA

It makes perfect sense, just with your taxes, that you should receive what is owed you. With the FAFSA, this affects your student’s financial aid award. Kim Clark of Time.com/Money shares her best advice on how to complete the form properly to ensure you get the most financial aid.

Read more . . .

Do me a favor and pass this information along to other parents. The more you know, the more you will maximize your financial aid. And…sharing is caring!

Mom-Approved Tips: Insist Your Student Graduate in 4 Years or Less


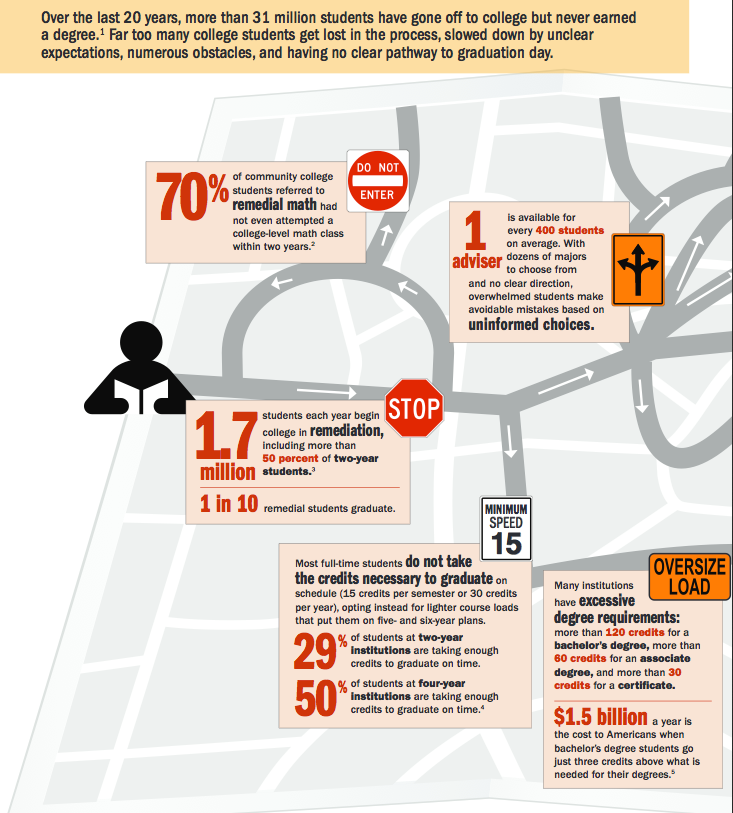
Did you know that at most public universities, only 19 percent of full-time students earn a bachelor’s degree in four years? Even at state flagship universities — selective, research-intensive institutions — only 36 percent of full-time students complete their bachelor’s degree on time.

Nationwide, only 50 of more than 580 public four-year institutions graduate a majority of their full-time students on time. Some of the causes of slow student progress are inability to register for required courses, credits lost in transfer and remediation sequences that do not work. Studying abroad can also contribute to added time and credits lost when abroad. According to a recent report from CompleteCollege.org some students take too few credits per semester to finish on time. The problem is even worse at community colleges, where 5 percent of full-time students earned an associate degree within two years, and 15.9 percent earned a one- to two-year certificate on time.

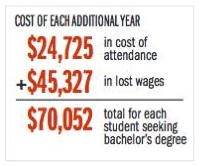
graduate in 4 yearsWhat is lost when a student doesn’t graduate in 4 years?

MONEY! My good friend, and college counselor, Paul Hemphill of Planning for College put it into perspective recently. (See chart to the right). It’s not just the cost of the education that your student loses, but the earning potential over the additional year or years. Nothing speaks louder than cold, hard numbers.

What can parents do to ensure on-time graduation?

It’s not a difficult task, although the numbers might speak otherwise. Taking control of the process and making a plan will go a long way in ensuring on-time graduation

Show your student the numbers—Nothing speaks louder than showing your student a loss of thousands of dollars in earning potential if they don’t graduate on time.

Help them plan their major and degree plan, ensuring it can be done in 4 years—Help them plan, ask questions of their advisors, and have solid discussions about their career and/or major.

Encourage AP testing and dual-credit courses—With AP testing and dual-credit courses, a student can enter college with multiple credits out of the way. The cost of these tests and courses pales in comparison to the cost of a college credit and extra money paid if they don’t graduate on time. It’s conceivable that with the right planning, a student can graduate in less than 4 years.

Attend community college for the basics during the summer before college—Not only will your student get some courses out of the way at a cheaper rate, they will enter college with credits under their belt.

Use some tough love—Explain the importance of graduating on time and explain that you will support them for 4 years only. After that, the cost is on them. Nothing motivates a teen more than realizing they will have to pay for college themselves.

Below is a neat little graphic (courtesy of Paul Hemphill) breaking it down for you.

graduate in 4 years

Edvisors: Demystifying Financial Aid

EdvisorsEdvisors

Get any two parents of college-bound teens together and the topic of financial aid is likely to come up. Every parent dreams of their son or daughter getting a free ride to college. It happens, but it takes some real determination and planning.

Mark Kantrowitz, the founder of FinAid, left that nationally recognized website last year to create a new online resource at Edvisors.com for parents and students to help them learn how to pay for college.

Topics covered

Here are some of the topics that you’ll find by spending time on Edvisors:

  • Student Aid Secrets for Increasing Eligibility
  • Eligibility Requirements for Financial Aid
  • Federal College Grants
  • How To Choose a Student Loan
  • Finding and Applying for Scholarships
  • Paying Back Parent and Student Federal Loans
  • Military Student Aid

Free Guide to Filing the FAFSA

On the Edvisors’ website, you can also download a free copy of  Filing the FAFSA:  The Edvisors Guide to Completing the Free Application for Federal Student Aid 2014-2015 Edition.

To download Filing the FAFSA you will have to provide information that will put you on Edvisors’ newsletter list, but you can always opt out if you prefer. As an alternative, you can also buy the 249-page paperback version on Amazon.

Education Tax Benefits

There is a section of the website that contains an excellent and informative explanation of federal education tax benefits. The section describes each tax benefit, and teaches you which are the optimal education tax benefits for your family:  Picking the Best Mix of Education Tax Credits and Benefits.

Asking for help

The site gives you an opportunity to post your financial aid questions in a section of the website entitled, Ask the Edvisors. You can also view previously asked questions and the answers provided by the site’s founder Mark Kantrowitz.

Spend some time navigating the site and discover valuable information regarding paying for your student’s college education.

How to Determine the True Cost of College


Parents and students are always looking for ways to determine the cost of college. It’s even more important as costs keep rising and with increasing student debt loads, families need more help than ever when making a college decision and determining the true cost of college.

Enter CostofLearning.com

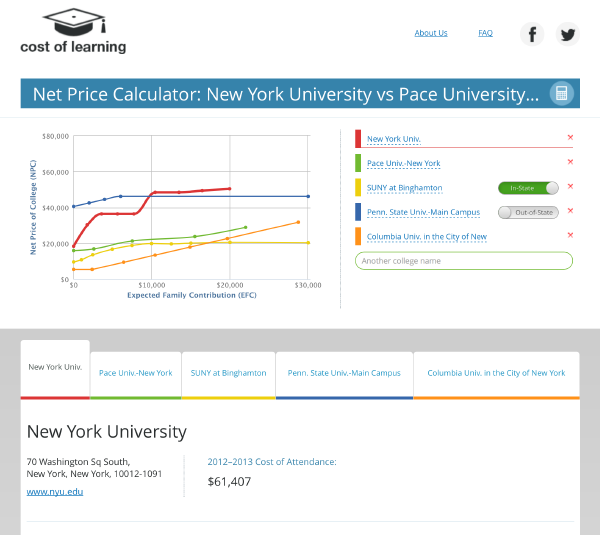
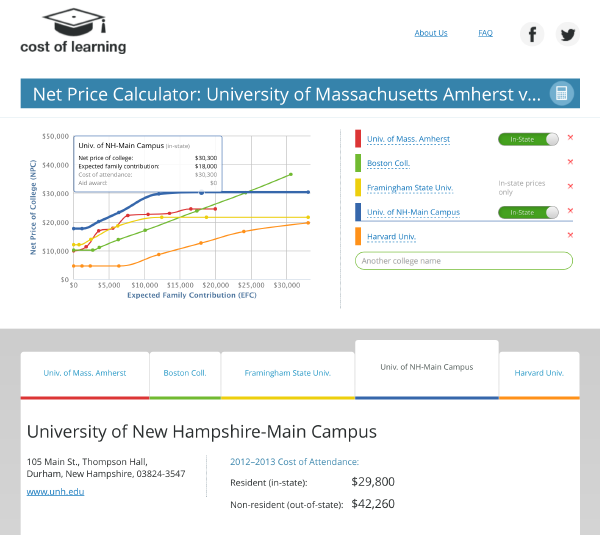
determine the true cost of collegeWith CostofLearning.com, a user simply selects one or more colleges and a chart appears showing Expected Family Contribution on one axis and the net cost on the other. The free service requires no inputting of personal financial information or registration.

Jimmy Becker, CostofLearning.com CEO, says “We have developed the first universal net price calculator that allows families to compare college pricing in a way they have never been able to before. With CostofLearning.com, what used to be a slow, financially intrusive, and confusing process, is now fast, clear and simple. Most importantly, families get transparency into net pricing.”

How does it work?

CostofLearning.com aggregates multiple data sources and uses proprietary data analysis and modeling to ensure accurate results. Until now, these data sources have never been combined in such a visual and easy-to-use format.

true cost of college“CostofLearning.com’s universal net price calculator reveals facts about schools that users may find surprising,” Rachel Okin, M. Ed, Founder of Okin College Match, and a college admission consultant. “Depending on a family’s financial status and state of residency, sometimes the college that a student expects to be the least expensive turns out not to be and vice versa.  The CostofLearning.com web app is a great tool to help families realize there are colleges they may not have thought they could afford that they actually can. I recommend it as part of the college search process.”

In addition, users can adjust for out-of-state vs. in-state tuitions as well as find more in-depth information such as endowment size, admissions statistics, test scores, graduation rates and more.

Mom-Approved Tips: What Are Your Priorities?


prioritiesEvery day parents complain about the high cost of college and the fact that even though they have saved, it’s not going to be enough to cover present day costs. When the kids enter high school, most parents begin to panic. The time has slipped away from them and they are faced with some difficult decisions. The thought of disappointing their kids seems unfathomable and the thought of telling their family and friends that they can’t afford to send their kids to college is even worse.

Consequently, we exhibit behavior that has devastating consequences for us and for our kids:

  • We make unwise decisions related to student loans
  • We neglect to tell our kids “no” when a college is beyond our ability to pay
  • We don’t include our kids in the financial aspects of the decision in the beginning

I read a post by Lynn O’Shaughnessy on The College Solution blog entitled “We are Done Paying for College”— it made me stop and think: what are our priorities as parents? Lynn and her husband began planning when their kids were little. They scrimped and saved and prepared for the day when they would go to college. It required sacrifice and commitment. But they did it and can say that their kids graduated without any student loan debt. You owe it to yourself to read her post, even if your kids are already in high school. It’s a definite wakeup call for all parents of college-bound teens.

Step back and evaluate

What are your priorities? Is college important enough for you to make some sacrifices? This means financial sacrifices and sacrifices of your time.

Make a plan and stick to it

If paying for college means driving an older model car for a few years, do it. If you need to supplement your education savings by taking on a second job and insisting your kids work during high school, make it work. If your family has to forgo some vacations, a new home, or a eating out often, it’s worth the sacrifice. But whatever you decide, make a plan and stick to it.

Be creative and think outside the box

There are so many creative ways to attain a college degree. Your kid isn’t bound to the typical four-year University or attending four consecutive years in a row. It’s also not necessarily essential that they attend college right out of high school. Do whatever it takes to attain the degree without debt and causing the family financial hardship.

It doesn’t matter where you are in the college prep process. You should evaluate your priorities and ask yourself some tough questions. It may sting in the beginning but once you’ve examined your options, you’ll sleep easier and so will your kids.

How to Decipher the Financial Aid Award Letter


financial aidAs the offers of admission arrive, the financial aid award letters will follow. If you’re a novice to the award letters, as most first time college parents are, they can be confusing and vague. Added to the confusion is that every award letter is different, making it hard to easily compare them side by side.

Thankfully, there are tools available and information to help you look at these letters for what they are: the college’s pitch for your student to accept their offer of admission. You are in control of this process and you hold the cards. It’s your decision to accept or reject their offer based on the amount of aid they are willing to give your student. Money, in this situation, is everything.

If a college wants your student to attend, they will back it up with money. No money, means their offer is probably based on filling a quota and them expecting you will decline to attend. And you should. Who wants to attend a college that doesn’t place value in your student?

But before you accept, reject, or negotiate with the college, you need to understand the award letter and its components.

Want to know more? Read an article I wrote for TeenLife:

How to Break Down the Financial Aid Award Letter


A Financial Aid Flowchart


Financial aid can be confusing for parents and students. From scholarships, to loans, to 529 funding, it can be an overwhelming process.

Student financial aid comes in all shapes and sizes – and one size doesn’t fit all when it comes to paying for college. With many different student loans to choose from, finding the optimal path to college funding can be tricky. eStudent Loans created this graphic to help those who need more than just scholarships and grants to fund their education and fund it in a way that will help save you money.

So, if you’re one of the thousands of students that are not sure where to start, relax. Simply use their financial aid flowchart to help you explore nearly every possible option available to help you cover the costs of earning your college degree. At the same time, they also show you the order in which you should pursue each funding source.

Financial Aid Flowchart: A Guide for Students Paying for College by eStudentLoan

Financial Aid Flowchart: A Guide for Students Paying for College from eStudentLoan

Download the interactive Financial Aid Flowchart

College Decisions To-Do List


college decisions
-photo courtesy of Zinch

For seniors, the New Year brings those long-awaited college decisions: deferred, accepted, rejected, and wait listed. One knowledgeable college counselor once told me, “I don’t like to call these letters of acceptance. I use the term—offers of admission.”

As a parent, I like that distinction. This alternative wording makes it easier to stomach those not-so-pleasant responses and help your college-bound teen work through the gamut of emotions that come when decisions arrive.

Your student may be the one receiving these communications from the colleges, but you feel every emotion they do from failure to excitement and everything in between. But unless you understand what each term means, it’s hard to know how to help your student (and yourself) with appropriate responses and proper action.

When the letters from the colleges (or online notifications) arrive, your student will receive one of four responses: deferred, wait-listed, rejected (declined admission) or accepted (offered admission). Once you understand these terms, you can determine what your response should be and how you need to take action.

Read more from Zinch: You’ve Heard from the Colleges–Now What?

Understanding Federal Student Loans


The FAFSA, based upon my 12 years of experience in working with college-bound high school students and their families, is a document that elicits terror and confusion. However, it really doesn’t have to be this way. I tell parents that the FAFSA really is simply an admission ticket to be considered for a wide range of college, state, and federal financial aid. In fact, parents can’t even qualify for any federal loans unless they fill out the FAFSA. If you don’t fill out the FAFSA, from a purely federal loan perspective, you don’t exist as a financial aid applicant to the federal government or the colleges.

The FAFSA website, surprisingly, is an excellent resource for most commonly-asked questions about how to complete the form. The form itself is remarkably user-friendly; if you fill it out electronically, which is how most families do it nowadays, the system will actually alert you to any potential errors when you’re entering information.

Rather than focus upon the mechanical aspects about the FAFSA, let me highlight two key general tips on the twin 500-pound gorillas of the federal loan world: subsidized and unsubsidized loans. These are the federal student loans that are frequently obtained via the FAFSA.
student loans

Subsidized student loans

Obviously a student would prefer a scholarship as opposed to a loan, but if you’re going to need a loan – and chances are you’re almost certainly going to have to borrow some money – then subsidized federal loans are the way to go. Interest rates are currently 3.86%, and the best part about these loans is that you don’t know owe any money or any interest until six months after you graduate (or fall below half-time status). And when I say graduate, I mean from your final degree program. Let’s say, for example, that you pursue a bachelors, Masters, and law degree without any breaks. You would only be responsible to repay the subsidized student loan six months after graduation from law school – even if you got your only subsidized student loan as a freshman in college. Even if you are able to fully pay for your college education, if you are offered a subsidized student loan why in the world would you not take it? It’s interest-free until your six-month grace period after graduation is over, in which case you can simply repay the loan in full, without penalty. In the meantime, your family would be able to invest that money in ways that (hopefully) generate income while the student is in college. If you truly do need the money, it’s nice to know that no interest is accumulating in the background while you are pursuing your studies.

In short, I can honestly think of no logical reason why a student wouldn’t accept the maximum in subsidized student loan funding for a given academic year.

Unsubsidized student loan

As the name implies, there are no taxpayer dollars going to pay off the interest while the student is in school. However, the student will not be expected to pay interest on the loan during his or her college, graduate, or professional education. Nonetheless, lurking in the background is the fact that unsubsidized loans are generating interest, and that they will have to be repaid six months after the student graduates (or falls below half-time status).

Why would someone take out these loans you might ask?

Well, unsubsidized student loans are still generally a better product than private sector loans. The interest rates are, like the subsidized student loans at the time of this writing, at 3.86% — clearly a better interest rate than what most private banks offer.

There’s another reason why I’m a fan of both the unsubsidized and subsidized loans from Uncle Sam. Let’s say a student gets into trouble and has a hard time repaying the lender. Although the federal government will expect full repayment – and forget about declaring bankruptcy to extinguish federal, state or private student loans because it’s virtually impossible to do so – in my experience the federal government will work more closely and more fairly with a delinquent applicant than will a private bank.

So when in doubt, take the federal loans as opposed to a private loan. They are both great loan programs and are the two loans most undergraduates will be offered if they and their parents complete the FAFSA.

______________________

About the Author

Today’s guest post is  from Jason Lum, the founder of ScholarEdge College Consulting.  Jason has won over $250,000 scholarships and graduated debt free.  Jason has helped students gain admission to some of the top universities in the country including Harvard, Yale and Stanford.  Follow him on Twitter and Facebook.